Puma continues business reset amid weak sales and profitability
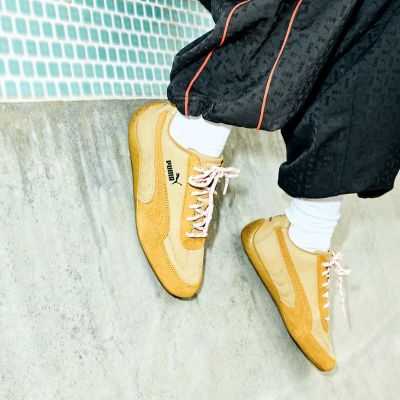
The Germany-based sportswear company reported lower sales and profitability in the third quarter of the year, reflecting the ongoing impact of its business reset and subdued consumer demand
“Our third-quarter performance was in line with expectations as we continued to move Puma through this transition year while laying the foundation for future growth”, said Arthur Hoeld, Chief Executive Officer of the company.
Third-Quarter Results
In the third quarter of the 2026 fiscal year, Puma reported sales of 1.78 billion euros, reflecting a 6.3% decline on a currency-adjusted basis (ca) and a 5.0% decline on a reported basis (as currency movements partially offset the decline in reported sales) compared to the same quarter last year.The company attributed this decline to the reset measures initiated in the third quarter of 2025, as well as the ongoing conflict in the Middle East, which has had a continued impact on consumer demand, particularly in EMEA and North America.
Sales in the EMEA region decreased by 11.5% (ca) year-on-year in the third quarter, amounting to 801.2 million euros. Although Puma’s direct-to-consumer (DTC) business grew slightly in the region, wholesale sales declined due to reduced undesirable business and subdued European demand linked to the conflict in the Middle East.
Sales in the Americas region decreased by 8.1% year-on-year to 580.4 million euros. This includes a 17.2% (ca) decrease in North America, mainly due to weaker consumer demand and reduced undesirable business with mass merchants, as well as a 1.4% (ca) increase in Latin America.
By contrast, Puma’s sales in the Asia Pacific region rose by 10.0% year-on-year in the third quarter, reaching 394.6 million euros, driven by sustained strong demand for low-profile sneakers. This increase includes a sales increase of around 3.5% in Greater China, driven by the DTC business in the region, and a sales increase of around 13.0% in the Asia-Pacific region, supported by strong wholesale performance across the region.
Compared to the third quarter of 2025, footwear sales declined by 5.1% (ca) to 1.02 billion euros, apparel sales by 9.4% (ca) to 557.1 million euros, and accessories sales by 3.2% (ca) to 208.1 million euros.
Supported by lower sourcing prices, Puma’s gross profit margin expanded by around 420 basis points year-on-year to 49.5%. Tariff refunds totalling 29.8 million euros contributed approximately 170 basis points to the overall improvement in the margin. Other factors that supported this improvement were a favourable channel mix, positive currency effects and lower freight expenses. However, an unfavourable product mix had an offsetting effect.
But while gross profit margin saw an improvement, higher operating expenses (OPEX) – which rose by 6.7% due to increased marketing, DTC and IT costs – had a negative impact on profitability. This, combined with lower sales, contributed to a fall in adjusted EBIT from 26.3 million euros a year earlier to 0.4 million euros. EBIT decreased from 16.2 million euros in the third quarter of 2025 to -11.4 million euros, resulting in an EBIT margin of -0.6%.
Full-Year Outlook
Puma still expects currency-adjusted sales to decline by a low to mid-single-digit percentage in the full year, mainly due to lower sales in North America and EMEA. This is due to measures to streamline distribution and a subdued consumer environment. Sales growth in Latin America and Asia/Pacific can only partially compensate for this.However, the company is now forecasting an operating result (EBIT) of between -80 million and -130 million euros (previously forecast as between -50 million and -150 million euros), including the effects of the cost efficiency programme that has been implemented.
Image Credits: hypebeast.com
Related news


Related Events
Related Organizations

-
-

World Footwear Public Calendar
Click here to subscribe an updated version of the calendar displaying the footwear trade shows.
-
-
-
Media Partners
Media Partners
-
Schuhkurier
ARS ARPEL
SERMA
UNIT Publishing House