Wolverine Worldwide raises again its full-year outlook
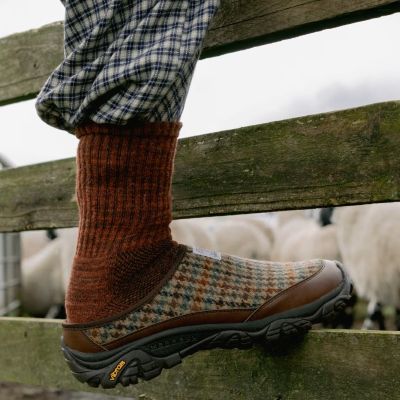
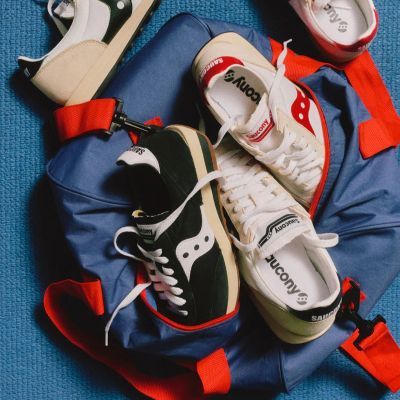
The US-based company has raised its outlook for the 2026 financial year again, following a strong performance in the third quarter driven by its two largest brands, Merrell and Saucony
“This quarter, now our eighth consecutive quarter of growth, is further evidence that our transformation story is also a growth story – with continued earnings improvement and a healthier balance sheet providing us greater capacity to invest behind our brands and the opportunities we see ahead”, said Chris Hufnagel, President and Chief Executive Officer of Wolverine Worldwide.
Third-Quarter Results
In the third quarter of the 2026 financial year, which ended on the 3rd of September, the company’s total revenue reached 505.4 million US dollars. This reflects an increase of 7.5% (or 7.7% on a constant currency basis) compared to the same period last year.During the period, Merrell contributed 178.2 million US dollars to the total revenue, up by 6.5% (or 6.8% on a constant currency basis) year-on-year, and Saucony contributed 158.9 million US dollars, up by 19.4% (or 19.7% on a constant currency basis) year-on-year.
Meanwhile, Wolverine recorded revenue of 43.5 million US dollars in the third quarter, a 4.1% decrease on both a reported and constant currency basis. Sweaty Betty recorded revenue of 41.4 million US dollars, a 7.0% decrease (or 6.5% on a constant currency basis) compared to the third quarter of 2025.
In the third quarter of 2026, IEEPA tariff refunds increased the gross, operating and adjusted operating margins by approximately 640 basis points each. Compared to the same period a year ago, gross margin rose from 47.5% to 54.6%, operating margin from 8.4% to 17.7%, and adjusted operating margin from 9.1% to 17.8%.
Wolverine Worldwide reported diluted earnings per share of 0.78 US dollars in the third quarter, up from 0.30 US dollars in the same quarter of 2025. Adjusted diluted earnings per share also increased, rising from 0.36 US dollars to 0.79 US dollars. IEEPA tariff refunds contributed approximately 31 cents per share to both measures.
As of the 3rd of October 2026, cash and cash equivalents increased by 10.6% to reach 148 million US dollars. Meanwhile, inventory decreased by 4.9% to reach 278 million US dollars, and net debt declined by 26.4% to reach 399 million US dollars year-on-year.
Full-Year Outlook
The company raised its full-year 2026 revenue outlook to between 2.00 and 2.01 billion US dollars, compared to previous guidance of between 1.98 and 2.00 billion US dollars. This represents constant currency growth of between 6.7% and 7.2% year-on-year.Gross margin is now expected to reach 48.7%, up from the previous forecast of 46.9%. Meanwhile, operating margin and adjusted operating margin are projected at 11.5% and 11.8% respectively, compared to previous forecasts of 9.5% and 9.9%.
Wolverine’s guidance on diluted earnings per share rose from 1.48 to 1.58 US dollars to 1.88 to 1.92 US dollars, while guidance on adjusted diluted earnings per share rose from 1.55 to 1.65 US dollars to 1.95 to 1.99 US dollars. Both figures include an estimated benefit of 0.32 US dollars from IEEPA tariff refunds.
Image Credits: hypebeast.com
Related news



Related Events
Related Organizations

-
-

World Footwear Public Calendar
Click here to subscribe an updated version of the calendar displaying the footwear trade shows.
-
-
-
-
Media Partners
Media Partners
-
SHOES-MAGAZINE.COM
Schuhkurier
SERMA
Revista del Calzado